• Insurance Quotes
  • Contact
  • Privacy Policy
  • Terms & Conditions
Wednesday, October 7, 2026
Insure Monkey
844-226-8876
  • Home
  • Low Cost Health Insurance
  • News
    • Health Insurance
    • Insurance for Business
    • Health Care
    • Medicare
    • Casualty Insurance
    • Insurance Education
    • Life Insurance
  • Contact
  • Home
  • Low Cost Health Insurance
  • News
    • Health Insurance
    • Insurance for Business
    • Health Care
    • Medicare
    • Casualty Insurance
    • Insurance Education
    • Life Insurance
  • Contact
No Result
View All Result
Morning News
No Result
View All Result
Home Life Insurance

Why Does Universal Life Insurance Have Such Low Guarantees • The Insurance Pro Blog

August 10, 2022
in Life Insurance
0
Why Does Universal Life Insurance Have Such Low Guarantees • The Insurance Pro Blog
0
SHARES
5
VIEWS
Share on FacebookShare on Twitter

READ ALSO

5 Checks Before You Sign

Where to Put Money After Maxing Out Your 401(k) and Roth

Podcast: Play in new window | Obtain

When taking a look at common life insurance coverage–particularly within the context of its means to build up money worth–and evaluating it to different life insurance coverage merchandise like entire life insurance coverage, folks usually word that it seems to have a lot decrease ensures.  The truth is, this is an excerpt from an listed common life insurance coverage proposal that highlights stated low assure:Universal Life Insurance Guaranteed PremiumNow, let me provide you with some background on this coverage to be able to perceive a number of the amazement over this data.
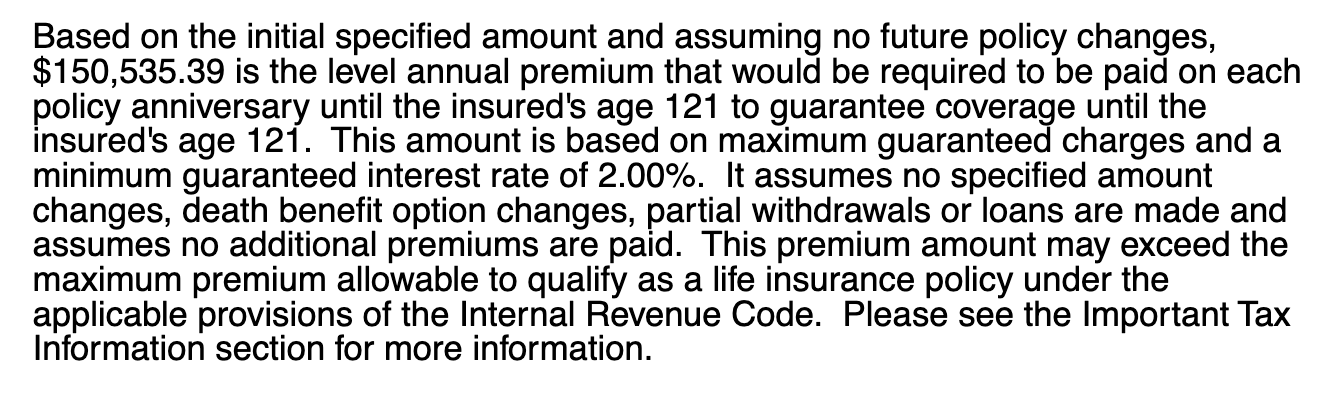
That is an listed common life insurance coverage coverage for a male age 45.  It has a dying profit quantity of $815,241.  In the event you’re questioning why the dying profit is such an odd quantity and never a neat spherical determine like $850,000 (for instance), it is as a result of this coverage was designed utilizing the deliberate premium quantity to calculate a essential dying profit (I will elaborate a bit extra on that in a bit).  The deliberate premium for this coverage is $50,000 yearly (most likely sounds extraordinarily excessive if you happen to’ve all the time considered life insurance coverage as an expense, however there’s one thing else we’re capturing for on this case).

As a result of this coverage design makes use of a minimal Non-Modified Endowment Contract dying profit and can also be complies with the Guideline Premium Check, that $50,000 premium is the utmost allowable with out inflicting considerably unfavorable tax penalties to the coverage.

See also  How Long Do I Have to File a Lawsuit Against New York Life?

…however the quoted textual content, which was taken immediately from the company-issued proposal, clearly states that if the would-be coverage proprietor needs to assure that his preliminary $815,241 dying profit stay in pressure to his 121st birthday, he a lot pay a whopping $150,535.39.  This sounds horrible.

And if he actually did want to assure his dying profit to his 121st birthday, this may be a fully horrible product selection.  However that is not the objective right here so this truth is…moot for essentially the most half.

Totally different Life Insurance coverage Insurance policies Have Totally different Goals

There are lots of life insurance coverage insurance policies on the market.  And this will likely come as a shock, however with all of this range of choices comes a range of aims tackled by completely different insurance policies.

Whereas many individuals understandably consider life insurance coverage as universally the identical–you pay a premium, and it pays a dying profit if you die–it isn’t.  Some insurance policies search to supply a low-cost dying profit.  Different insurance policies search to supply a excessive accumulation of money worth.  Typically talking, these two aims are on opposing sides of a advantages spectrum.

If the person on this scenario wished to ensure an $815,241 dying profit to his age 121, there are merchandise that might do it for a lot lower than $50,000 per year-say nothing in regards to the $150,535.39.

But when, however, he desires to realize the best charge of return on a $50,000 annual cost right into a life insurance coverage coverage to construct wealth that enjoys many tax advantages, this product is arguably one of the best at the moment accessible available on the market.

See also  Top 5 Health Insurance Companies In The U.S.

Life Insurance coverage Ensures Price Cash

Life insurance coverage ensures price cash.  That is true for each the insurance coverage firm and the coverage proprietor.  The insurance coverage firm should shoulder the danger related to the dying assure and have ample reserves (i.e. cash it holds however may be very restricted in funding choices) to show it might make good on the assure.  This price is mostly realized to the coverage proprietor via a lesser money worth accumulation on the coverage.

Insurance coverage firms are keenly conscious of this tradeoff, and produce merchandise to market that sacrifice ensures in favor of offering far more engaging non-guaranteed options–often expressed via money worth accumulation.

So in our instance above, the product in query has such a low assure relating to the dying profit as a result of it additionally has a particularly excessive potential to supply non-guaranteed money worth.  The insurance coverage firm stripped excessive dying profit ensures from the product with the intention to afford the power to supply such greater money accumulating options.

The identical firm gives different common life insurance coverage merchandise.  They’ve greater ensures.  They may virtually positively accumulate a lot decrease quantities of money worth for a similar premium as our 45-year-old male insured.

Associated

Tags: BlogGuaranteesInsuranceLifeProUniversal

Related Posts

5 Checks Before You Sign
Life Insurance

5 Checks Before You Sign

October 3, 2026
The Case for Guaranteed Retirement Income • The Insurance Pro Blog
Life Insurance

Where to Put Money After Maxing Out Your 401(k) and Roth

September 21, 2026
The Case for Guaranteed Retirement Income • The Insurance Pro Blog
Life Insurance

Whole Life Policy Loans to Finance Inventory: A Business-Owner Case Study

September 19, 2026
The Case for Guaranteed Retirement Income • The Insurance Pro Blog
Life Insurance

Which Annuity Solves Which Problem?

September 19, 2026
The Case for Guaranteed Retirement Income • The Insurance Pro Blog
Life Insurance

How Much Cash Value Life Insurance Can You Afford to Fund?

September 18, 2026
The Case for Guaranteed Retirement Income • The Insurance Pro Blog
Life Insurance

Your Buy-Sell Agreement Is Probably Already Underfunded

September 10, 2026
Next Post
Think you’re not eligible for ACA subsidies? Think again.

Think you're not eligible for ACA subsidies? Think again.

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

POPULAR ARTICLES

How price shopping for health care can save you money (and how to do it)

How price shopping for health care can save you money (and how to do it)

August 1, 2022
Police Life Insurance [The Top 7 Job Risks that May Affect Your Rate!]

Police Life Insurance [The Top 7 Job Risks that May Affect Your Rate!]

March 31, 2023
Watch: Explaining the Nitty-Gritty of Medicare Drug Price Negotiations — And Patients’ Potential Savings

Watch: Explaining the Nitty-Gritty of Medicare Drug Price Negotiations — And Patients’ Potential Savings

August 1, 2022
Hospices Have Become Big Business for Private Equity Firms, Raising Concerns About End-of-Life Care

Hospices Have Become Big Business for Private Equity Firms, Raising Concerns About End-of-Life Care

August 1, 2022
Get Inflation Beating Retirement Income with Whole Life Insurance • The Insurance Pro Blog

Get Inflation Beating Retirement Income with Whole Life Insurance • The Insurance Pro Blog

October 6, 2022

EDITOR'S PICK

‘Dreamers’ Enrolling in Obamacare Will Add Billions to Deficit

‘Dreamers’ Enrolling in Obamacare Will Add Billions to Deficit

June 26, 2024
As Insurance Prices Rise, Families Puzzle Over Options

As Insurance Prices Rise, Families Puzzle Over Options

January 17, 2026
California Stockpiles Penalties From Uninsured Residents Instead of Lowering Care Costs

California acumula multas de residentes sin seguro en lugar de reducir los costos de la atención

November 20, 2022
Numbers Don’t Lie. Biden Kept His Promise on Improving Obamacare.

Numbers Don’t Lie. Biden Kept His Promise on Improving Obamacare.

January 18, 2023

About

Insure Monkey is a free service to assist users in getting insurance quotes from insurance providers. Insure Monkey is not affiliated with any state or government agency. Insure Monkey is not an insurance agency or broker, nor an insurance referral service. Insure Monkey does not endorse or recommend any participating Third-Party Insurance Providers that pay to participate in this advertising.

Categories

  • Auto Insurance
  • Casualty Insurance
  • Health Care
  • Health Insurance
  • Insurance Education
  • Insurance for Business
  • Life Insurance
  • Medicare
  • Uncategorized

Recent Posts

  • Learn about Independence Blue Cross 2025 Medicare offerings and sign up for a plan while at select ShopRite, The Fresh Grocer, and Price Rite locations this fall
  • Before Saying Yes to the Medical Test, Know the Risks and Benefits
  • How Do I Know If I Have a Valid Disability Claim Against Lincoln Financial?

Newsletter

  • Insurance Quotes
  • Contact
  • Privacy Policy
  • Terms & Conditions

© 2024 Insure Monkey - All rights reserved.

No Result
View All Result
  • Home
  • Low Cost Health Insurance
  • News
    • Health Insurance
    • Insurance for Business
    • Health Care
    • Medicare
    • Casualty Insurance
    • Insurance Education
    • Life Insurance
  • Contact

© 2024 Insure Monkey - All rights reserved.