


As its identify implies, dividend paying entire life insurance coverage is a type of entire life insurance coverage that earns a dividend. The official insurance coverage time period used to establish a dividend paying entire life coverage is “collaborating” as a result of the coverage participates within the divisible surplus (i.e. income) of the insurance coverage firm.
The choice to a dividend paying entire life coverage is a non-dividend paying (additionally known as non-participating or non-par) entire life insurance policies. As soon as a non-dividend paying entire life coverage is issued, it is going to by no means earn a dividend no matter how worthwhile the insurance coverage firm is. A dividend-paying entire life coverage, alternatively, is eligible to dividends, however this doesn’t all the time means it is going to earn dividends.
Life insurance coverage dividends present a whole lot of worth that improve varied options of a complete life coverage past the assured options. Life insurance coverage dividends additionally get pleasure from a number of tax favorable advantages.
How do Complete Life Dividends Work?
Annually the life insurance coverage firm’s board of administrators appears at firm income and decides how a lot of those income to pay to policyholders who personal dividend-paying insurance policies. As soon as declared, the policyholder will earn the dividend on the subsequent coverage anniversary. The dividend earned will go in direction of no matter dividend possibility the coverage proprietor presently chosen.
It is essential to grasp that whereas the dividend fee can develop over time, the forces that have an effect on a rising dividend fluctuate. This implies the precise dividend fee could also be kind of than the earlier 12 months’s dividend fee. I convey this up as a result of most life insurance coverage ledgers historically assume a state of affairs the place dividend funds repeatedly enhance. Whereas that is doable, it is hardly ever the way in which issues works out in actual life.
How do Dividends Have an effect on A Complete Life Coverage’s Money Worth?
Dividends can improve a complete life coverage’s money worth by means of the paid-up additions dividend possibility. This feature makes use of the dividend to buy extra mini entire life insurance policies which might be instantly paid-up and have instant money worth. These insurance policies connect to your entire life coverage and their loss of life profit and money worth provides to your entire life coverage’s loss of life profit and money worth.
Moreover, these paid-up additions can earn dividends so you’re successfully compounding the expansion of your entire life coverage with this selection. The Dividend purchases paid-up additions, which can earn extra dividends. These extra dividends will buy much more paid-up additions, which in flip will go in direction of the acquisition of much more paid-up additions.
How do Dividends Have an effect on A Complete Life Coverage’s Dying Profit?
Dividends can have an effect on the loss of life profit of a complete life coverage in two methods.
First, using paid-up additions may also enhance loss of life profit. For each $1 that goes in direction of a paid-up additions, you’ll obtain some a number of of loss of life profit (e.g. $1 used in direction of paid-up additions would possibly create $3 in loss of life profit). The precise quantity varies relying on the age of the insured of the coverage. As we already coated, paid-up additions will compound as a result of they themselves earn dividends sooner or later. It will trigger your general entire life loss of life profit to develop exponentially as time goes on.
Second, most entire life insurance policies have a dividend choice to buy time period life insurance coverage. This makes use of the dividend fee to buy time period life insurance coverage that provides to the gross loss of life good thing about your entire life coverage. It will actually increase how a lot loss of life profit you obtain together with your coverage. As a result of it’s time period insurance coverage, you need to perceive that his loss of life profit is just not everlasting. You must also perceive that you’d select this selection alternatively to paid-up additions, so you may have to weigh which one offers you extra of what you’re searching for each now and sooner or later. This dividend possibility will do nothing for accumulating money worth in your entire life coverage.
What Causes the Dividend Fee to Go Up?
There are two variable behind an growing dividend fee over time. As soon as variable the policyholder can management. That is using the paid-up additions dividend possibility, or making elective paid-up addition funds by means of a selected rider.
The opposite variable is the profitability of the insurance coverage firm. If the insurance coverage firm turns into extra worthwhile year-over-year, there’s a good likelihood the corporate will enhance the dividend payable to policyholders. It is price noting that almost all dividend-paying entire life insurance policies come from mutual life insurance coverage corporations. These kind of insurance coverage firm place possession within the firm within the arms of the policyholders, so these corporations work completely for the advantage of policyholders. Given this construction, it is sensible {that a} extra worthwhile mutual life insurance coverage firm is eager to pay extra dividends to its policyholders.
What Causes the Dividend Fee to Go Down?
Once more, the forces that trigger a dividend to say no are partly as much as the coverage proprietor and partly as much as the life insurance coverage firm. Examples that trigger a dividend to go down embrace: the coverage house owners withdrawal of sure money values from the coverage, the set off of a scale back paid-up nonforfeiture profit, and the life insurer’s decline in profitability from one 12 months to the subsequent.
Are you able to Withdraw Dividends from a Complete Life Coverage?
Sure you may withdraw dividends from a complete life coverage. There are two major methods you go about doing this.
First, you should use the dividend choice to obtain the dividend fee in money. It will lead to a direct fee of the dividend to you annually. The insurance coverage firm can pay you regardless of the calculated dividend payable in your entire life coverage is as a money dividend despatched as a examine across the time of your coverage anniversary.
The second possibility in case you are utilizing the paid-up additions dividend possibility, is to request a withdrawal from the coverage (some corporations will particularly name this a withdrawal of dividend additions). This leads to a give up of the paid-up additions bought with dividends. It will lead to a discount of the general loss of life profit on the coverage (loss of life profit created by the paid-up additions you’re withdrawing). You’ll then obtain a examine within the quantity of the money worth of the paid-up additions you requested to withdraw.
Are Complete Life Dividends Taxable?
Complete life dividends have a number of tax favorable options that make the fee of dividends largely non-taxable to you. Generally, dividend aren’t taxable, however there are a couple of circumstances that might make them taxable.
First, in case you are taking the dividend as a money fee it’s normally a non-taxable fee. There are circumstances that might develop over time that may change this. The precise circumstances is a fee of dividends that exceeds your coverage price foundation.
For instance, assume that you just personal a complete life coverage into which you paid a complete of $50,000 in premiums. You opted to obtain the dividend as a money fee and starting this 12 months, the entire dividends paid to you from inception of the coverage equals $55,000. You’ll owe taxes on $5,000 in dividends and can now owe taxes on all future dividends acquired in case you pay no additional premiums into the coverage.
Second, in case you decide to withdraw money out of your coverage and also you withdraw a sum in extra of the premiums you paid into the coverage, you’ll owe taxes on the quantity withdrawn above the sum of the premiums you paid.
For instance assume the identical state of affairs above the place you could have a complete life coverage into which you paid $50,000 in premiums. Let’s additionally assume that you’ve got $110,000 in money worth on this coverage. Additionally assume on this state of affairs that you just used the dividend choice to buy paid-up additions in all years. You select to withdraw $65,000 from the coverage. You’ll owe taxes on $15,000 of this withdrawal as a result of that’s the distinction between what you paid in premiums and what you faraway from the coverage. Additionally any subsequent withdrawals can be taxable until you proceed to make premium funds.
Historic Complete Life Dividend Chart
Complete life dividends can and do change over time. Here is a chart that maps out adjustments amongst varied entire life corporations over the previous 20 years:
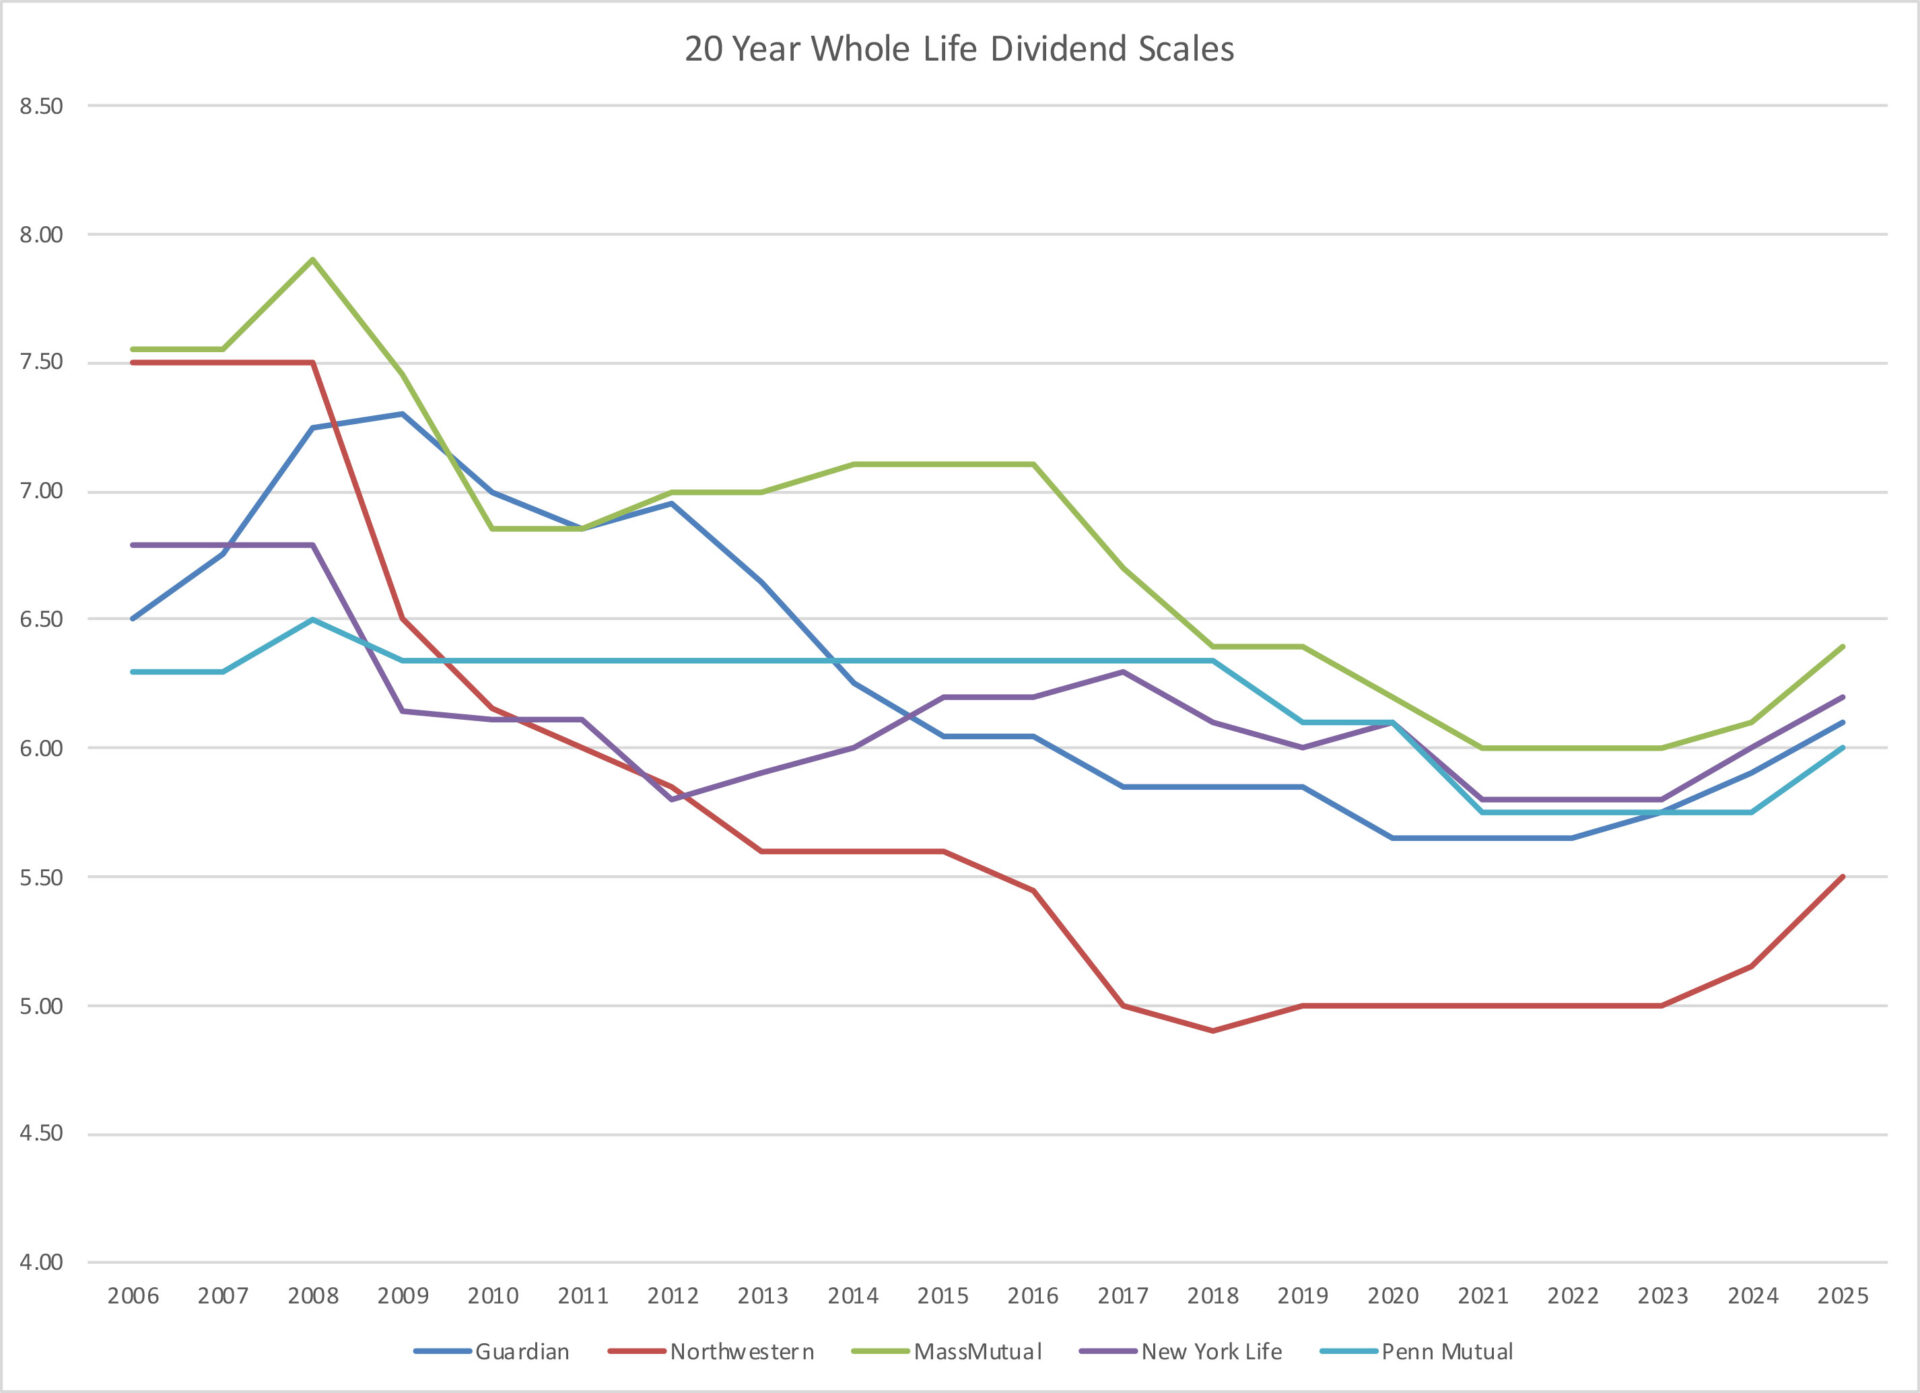
Two main observations from this chart are 1.) entire life dividend charges have a tendency to stay shut throughout corporations and a couple of.) some corporations modified their dividend charge way more considerably over this time interval than others. Remember the fact that the dividend charge is just not a unified metric and one firm’s charge is just not instantly comparable to a different. We are able to achieve some perception from trying on the charge of change at one firm to check to a different, however we can’t examine absolutely the dividend charge worth amongst life insurance coverage corporations.
The general development is a decline adopted by a reversal unfolding given present financial situations. Life insurers realized substantial will increase in funding profitability as rates of interest rose following the COVID Pandemic.


